
11420 Suggie Ln
Redding, CA 96003
$450,000
3 bd · 2.5 ba · 2,015 sqft · Listed 25d ago
View on Realtor.com →Year built
1986
Sqft
2,015
Lot sqft
106,286
HOA / mo
$0
Furnished
No
List date
2026-09-04T07:17:11.000000Z
Revenue
Annual revenue
$38,434
ADR
$155
Occupancy
68%
Cleaning fees (12 mo)
$6,914
Confidence
Low (32.57), 5 comps
Comp revenue range (p25 / median / p75)
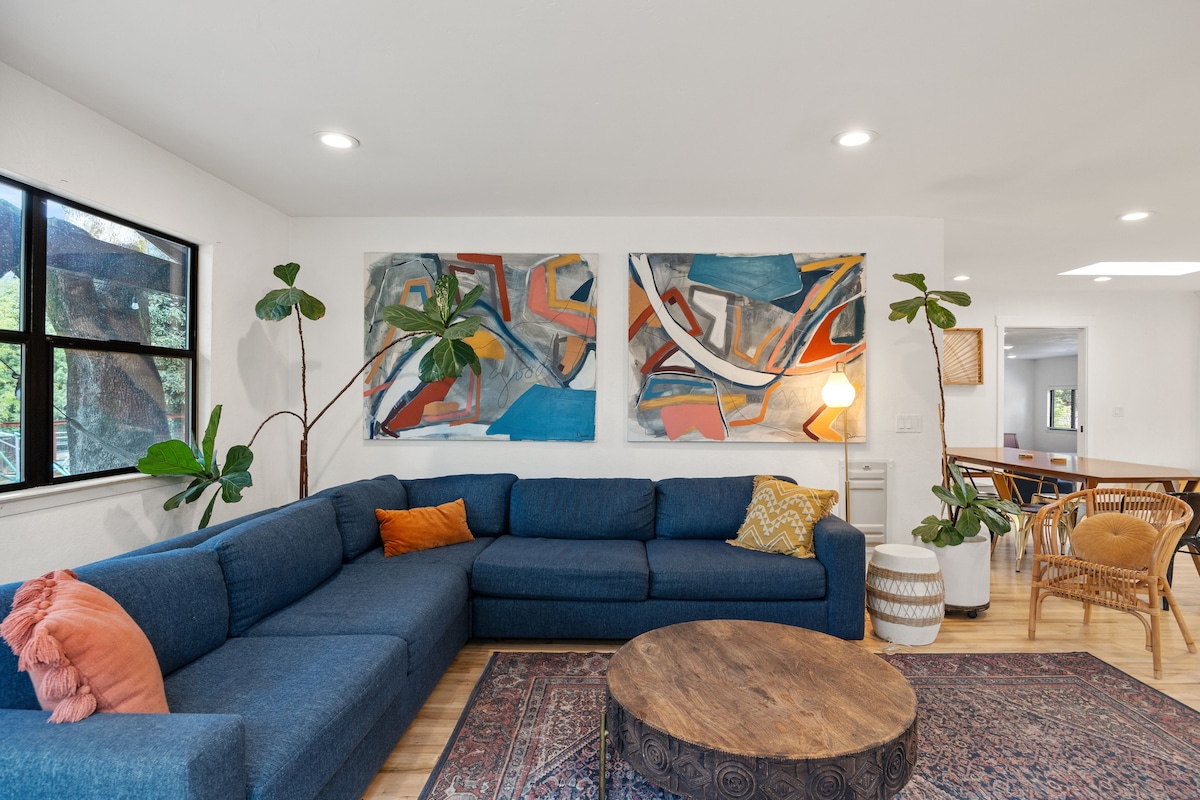

Peaceful Craftsman on Acres w/Labyrinth
House · 3 bd · 2 ba · sleeps 5 · 0.4 mi
Revenue $24,334ADR $205Occ ≈ 33%4.9★ (9)
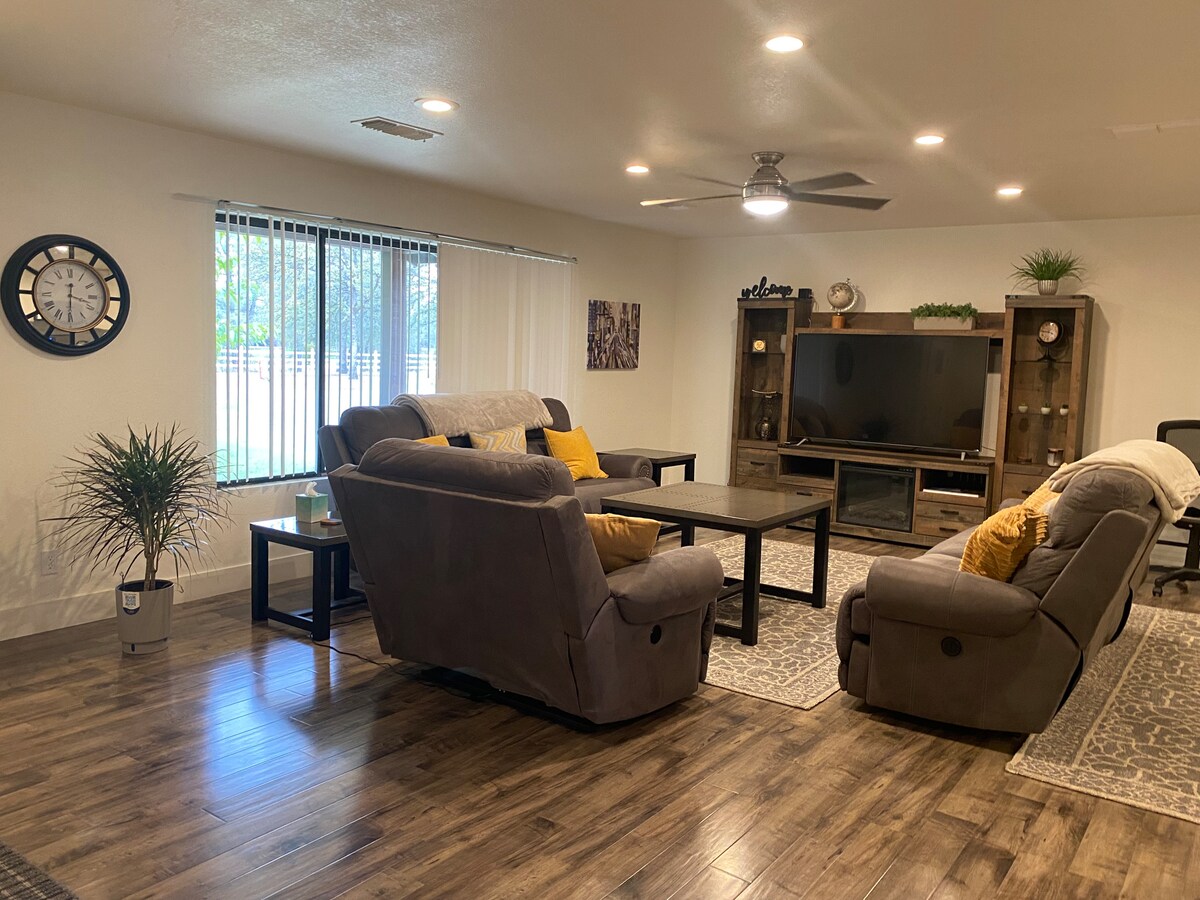
Small Country Home on 3 Acres Close to Town
House · 3 bd · 2 ba · sleeps 6 · 1.3 mi
Revenue $10,188ADR $81Occ ≈ 34%5★ (1)
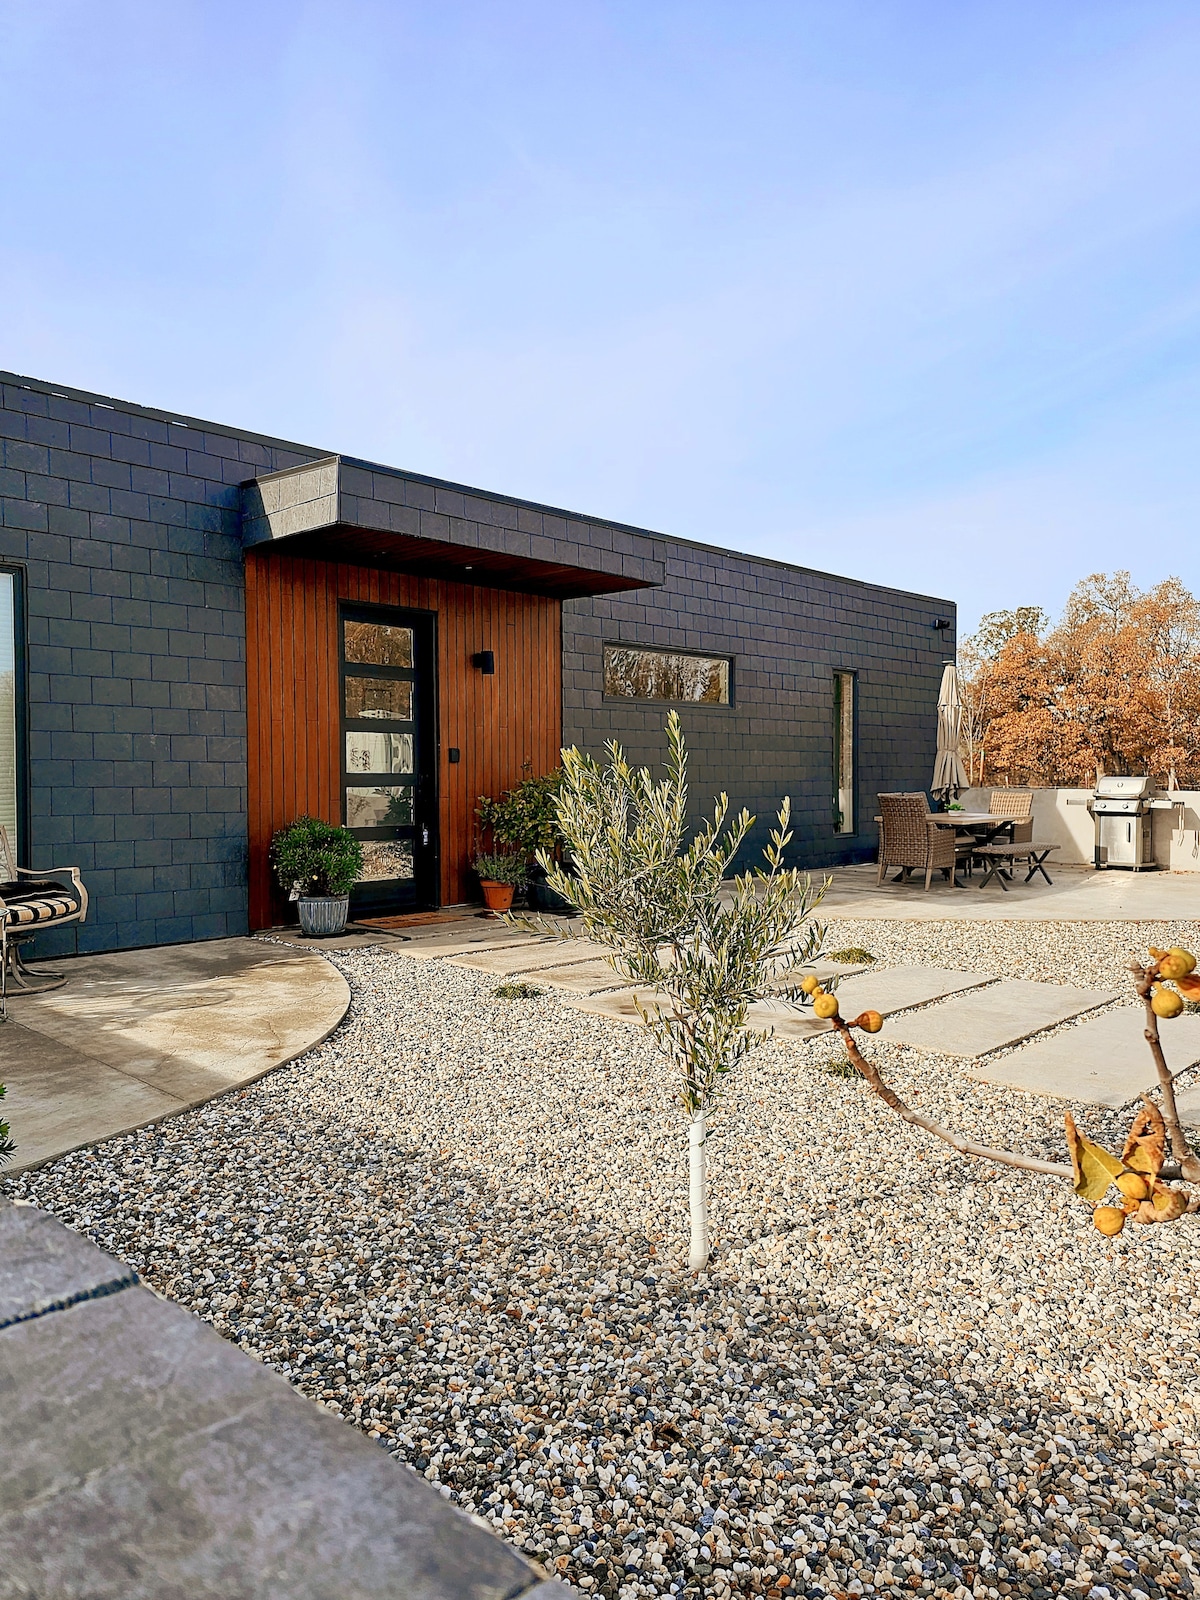
5 Acre Modern Redding Retreat + Hot Tub + Views
House · 2 bd · 1.5 ba · sleeps 5 · 1.4 mi
Revenue $73,778ADR $246Occ ≈ 82%5★ (219)
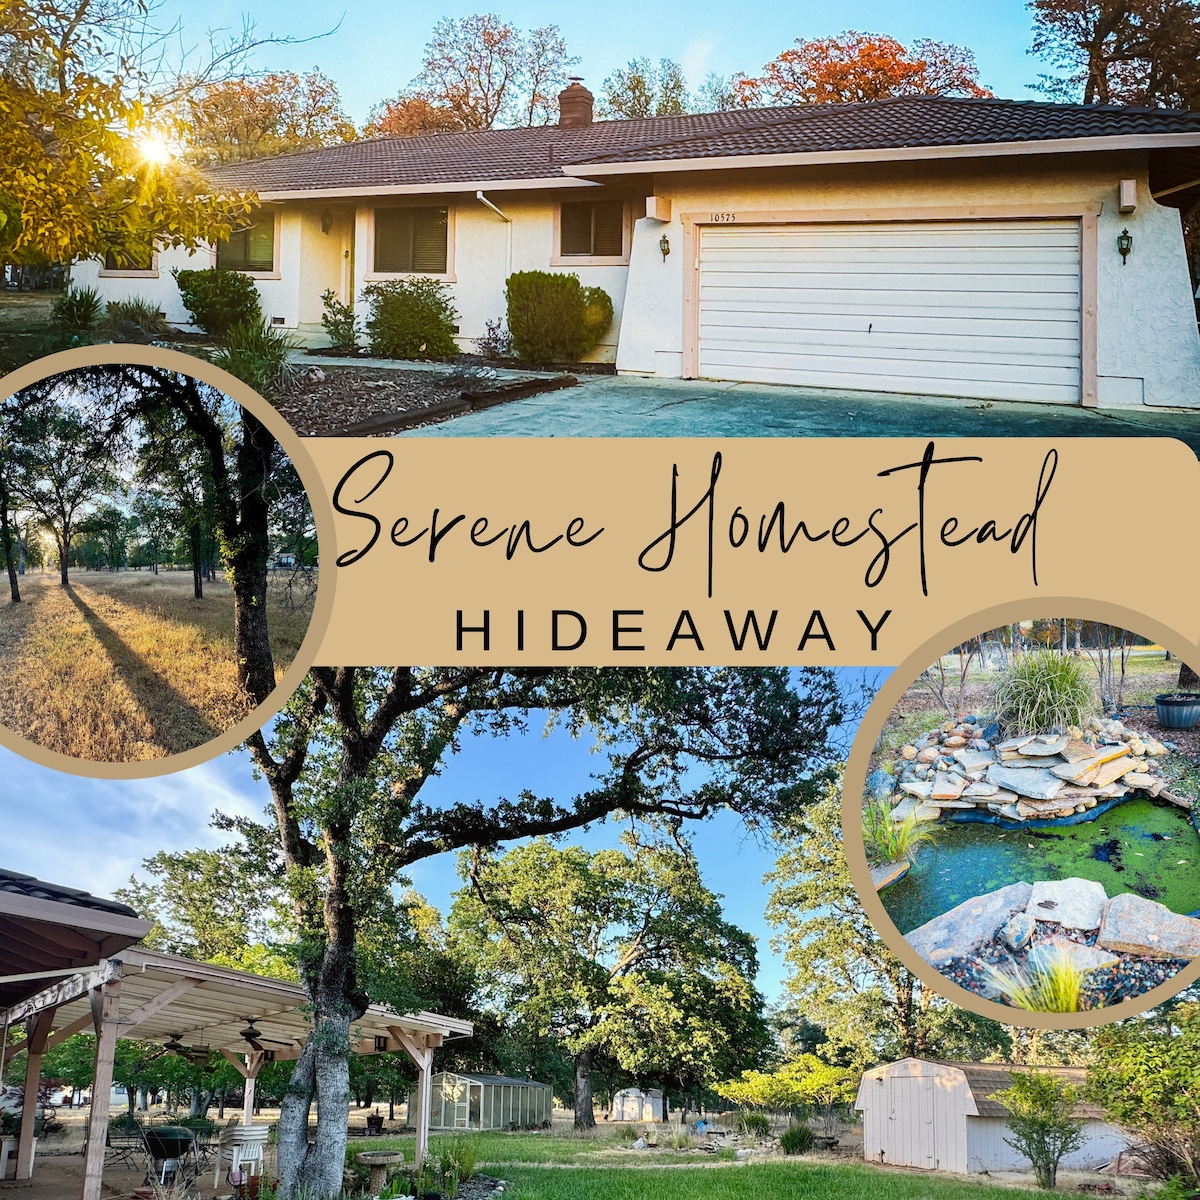
Serene Homestead Hideaway
House · 3 bd · 2 ba · sleeps 6 · 1.7 mi
Revenue $27,057ADR $148Occ ≈ 50%4.7★ (21)
| Listing | Size | Revenue (12 mo) | ADR | Occ ≈ | Rating | Distance | Links |
|---|---|---|---|---|---|---|---|
Peaceful Craftsman | Outdoor Space | Low Toxicity House | 3 bd · 2 ba · sleeps 6 | $50,951 | $253 | 55% | 4.7★ (20) | 0.4 mi | AirbnbVrbo |
Peaceful Craftsman on Acres w/Labyrinth House | 3 bd · 2 ba · sleeps 5 | $24,334 | $205 | 33% | 4.9★ (9) | 0.4 mi | Airbnb |
Small Country Home on 3 Acres Close to Town House | 3 bd · 2 ba · sleeps 6 | $10,188 | $81 | 34% | 5★ (1) | 1.3 mi | Airbnb |
5 Acre Modern Redding Retreat + Hot Tub + Views House | 2 bd · 1.5 ba · sleeps 5 | $73,778 | $246 | 82% | 5★ (219) | 1.4 mi | Airbnb |
Serene Homestead Hideaway House | 3 bd · 2 ba · sleeps 6 | $27,057 | $148 | 50% | 4.7★ (21) | 1.7 mi | Airbnb |
Revenue and nightly rate (ADR) are trailing-12-month figures per listing. Occupancy is estimated as revenue ÷ ADR ÷ 365 and can read high when revenue includes cleaning fees.
Cash flow calculator
Est. revenue
$38,434
NOI
$15,890
Cash flow /mo
$1,324
Cash needed
$487,500
Cash-on-cash (all cash)
3.3%
ROE (yr 1)
6.0%
Cap rate
3.5%
DSCR
—
Year-1 write-off
$96,011
Year-1 tax shield @ 32%
$30,724
Year-1 return on equity
- Cash flow (annual)$15,890
- Principal paydown (n/a, cash)$0
- Appreciation at%$13,500
Opex, cash-needed & tax-savings breakdown
Annual operating expenses
- Management (20% of revenue)$7,687
- Platform fees (3% of revenue)$1,153
- Maintenance / capex (5% of revenue)$1,922
- Utilities & supplies$4,200
- HOA$0
- Property tax$5,625
- Insurance (STR-rated)$2,633
Cash needed to close
- Purchase price (all cash)$450,000
- Closing costs (4.0%)$18,000
- Furnishing (bought new)$19,500
Tax savings if the STR loophole applies
- Tax shield @ 32%$30,724
Property tax, insurance rate and the land/building split come from this listing's county tax record; other assumptions match the daily feed (see tasks/plan.md).
The write-off comes from the cost segregation estimate below. Not tax advice.
Cost segregation estimate
An estimate from the listing: every part of the home is priced from national construction costs, less wear for age, and the price (less land) is spread over the parts in proportion. The headline is what a typical cost seg study would claim for this property. The answers below are optional refinements.
Depreciable basis
$319,000
Short-life (5/15-yr)
$76,000 · 24%
Year-1 deduction
$96,000
Year-1 tax shield @ 32%
$31,000
Land 29% (county tax record, assessed value split) · building $243,000 over 39 years · new furniture $20,000
Based on: 2,015 sq ft, built 1986, 3 bd / 2.5 ba, unfurnished, listing features (fence, fireplace, flooring types, septic).
IRS-guide safe-harbor floor: $76,000 in year 1 (17% short-life, $24,000 tax shield), the conservative amount following the IRS audit guide's residential classification table.
- $8,000
Kitchen cabinetsdefault
$10,200 new × 40% good × 1.97 allocation
- $6,600
Kitchen countertopsdefault
$8,400 new × 40% good × 1.97 allocation
- $2,800
Decorative trimdefault
$3,500 new × 40% good × 1.97 allocation
- $200
Mirrorsdefault
$300 new × 40% good × 1.97 allocation
- $900
Shelvingdefault
$1,200 new × 40% good × 1.97 allocation
- $3,900
Window coverings (20)default
$5,000 new × 40% good × 1.97 allocation
- $6,800
Carpet, vinyl & laminate (67% of floors)listing
$8,600 new × 40% good × 1.97 allocation
- $6,300
Kitchen & laundry equipment plumbingdefault
$7,900 new × 40% good × 1.97 allocation
- $3,800
Kitchen, laundry & data equipment electricaldefault
$4,800 new × 40% good × 1.97 allocation
- $6,400
Appliances (range, microwave, dishwasher, disposal, refrigerator, washer, dryer)default
$8,100 new × 40% good × 1.97 allocation
- $19,500
Furniture bought newlisting
$19,500 new × 100% good · bought separately
- $11,400
Paving: driveway & walks (paved)default
$11,600 new × 50% good × 1.97 allocation
- $8,800
Landscaping (typical)default
$9,000 new × 50% good × 1.97 allocation
- $2,000
Patiosdefault
$2,000 new × 50% good × 1.97 allocation
- $2,000
Decks & porches (attached)default
$2,000 new × 50% good × 1.97 allocation
- $5,900
Fencinglisting
$6,000 new × 50% good × 1.97 allocation
- $172,000
Structure: foundation, framing, walls, windows, doors, roof, interior finishesdefault
$218,700 new × 40% good × 1.97 allocation
- $17,800
Building plumbing & fixturesdefault
$22,700 new × 40% good × 1.97 allocation
- $17,900
Building electrical & lightingdefault
$22,800 new × 40% good × 1.97 allocation
- $17,900
HVACdefault
$22,700 new × 40% good × 1.97 allocation
- $3,400
Hardwood & tile floorsdefault
$4,300 new × 40% good × 1.97 allocation
- $2,100
Fireplacelisting
$2,600 new × 40% good × 1.97 allocation
- $11,800
Septic systemlisting
$12,000 new × 50% good × 1.97 allocation
About the property
Depreciation schedule: typical cost seg study
| Year | 5-yr | 15-yr | Building | Total |
|---|---|---|---|---|
| 1 | $65,200 | $30,000 | $800 | $96,000 |
| 2 | $0 | $0 | $6,200 | $6,200 |
| 3 | $0 | $0 | $6,200 | $6,200 |
| 4 | $0 | $0 | $6,200 | $6,200 |
| 5 | $0 | $0 | $6,200 | $6,200 |
| 6+ | $0 | $0 | $217,200 | $217,200 |
| Total | $65,200 | $30,000 | $242,800 | $338,100 |
Model-based estimate, not an engineered cost segregation study. The IRS doesn’t approve studies; get a professional study before filing. Using these losses against W-2 income needs the short-term rental exception (average stay ≤7 days + material participation). The 39-year building life applies because stays average under 30 days, a separate test (27.5 years for a long-term rental). Federal only: California and Georgia disallow bonus depreciation, Ohio adds back 5/6 of it, and Tennessee has no personal income tax. Not tax advice.
Market note
Rules differ by jurisdiction. City of Redding caps whole-home vacation rentals at 400 with a 600 ft spacing rule (300 ft with a physical buffer), and its permit is NOT transferable to a new owner. Shasta Lake city and unincorporated Shasta County allow permitted rentals with no cap found, but permits also do not transfer on sale. Lodging tax ~10% plus a 2% tourism assessment in Redding. Verify parcel eligibility with the city or county before you buy.