
3701 Laurel St
Shasta Lake, CA 96019
$314,900
3 bd · 2 ba · 1,156 sqft · Listed today
View on Realtor.com →Year built
1981
Sqft
1,156
Lot sqft
6,970
HOA / mo
$0
Furnished
No
List date
2026-10-16T00:30:04.000000Z
Revenue
Annual revenue
$42,798
ADR
$182
Occupancy
64%
Cleaning fees (12 mo)
$6,994
Confidence
Med (67.19), 5 comps
Comp revenue range (p25 / median / p75)
Median revenue of shown comps: $45,728
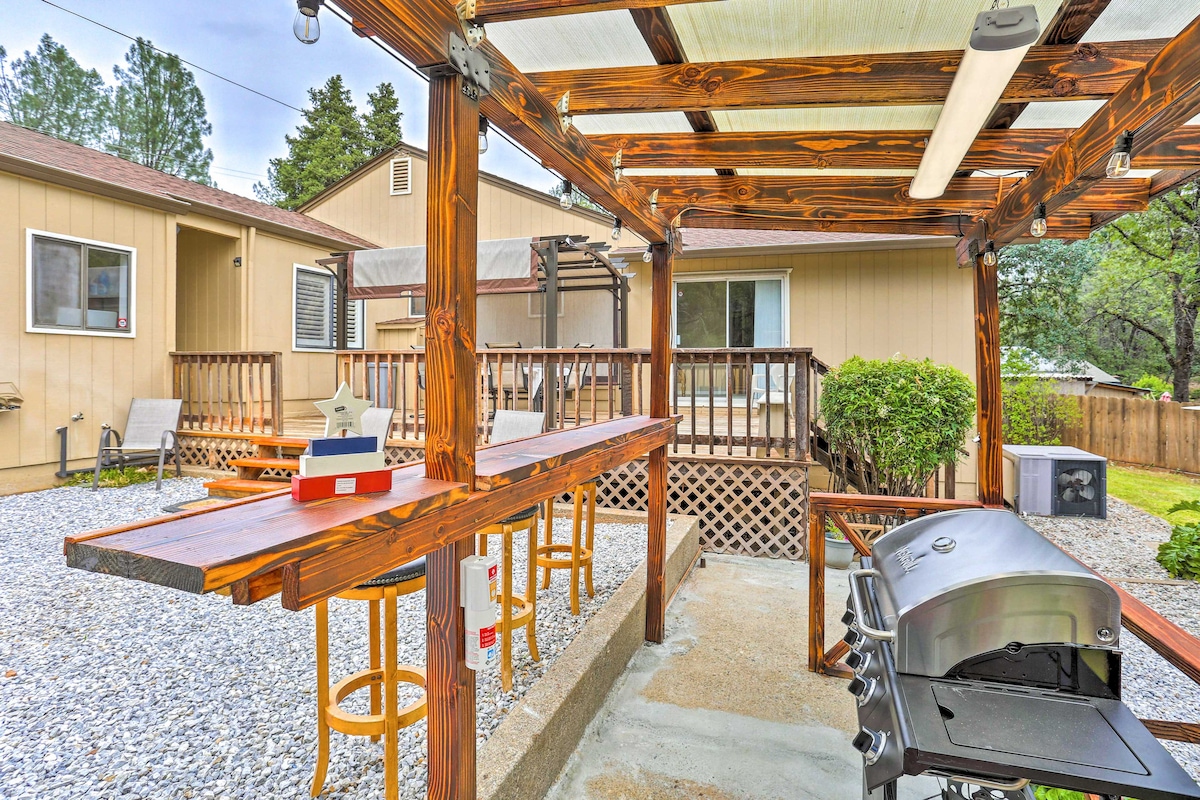

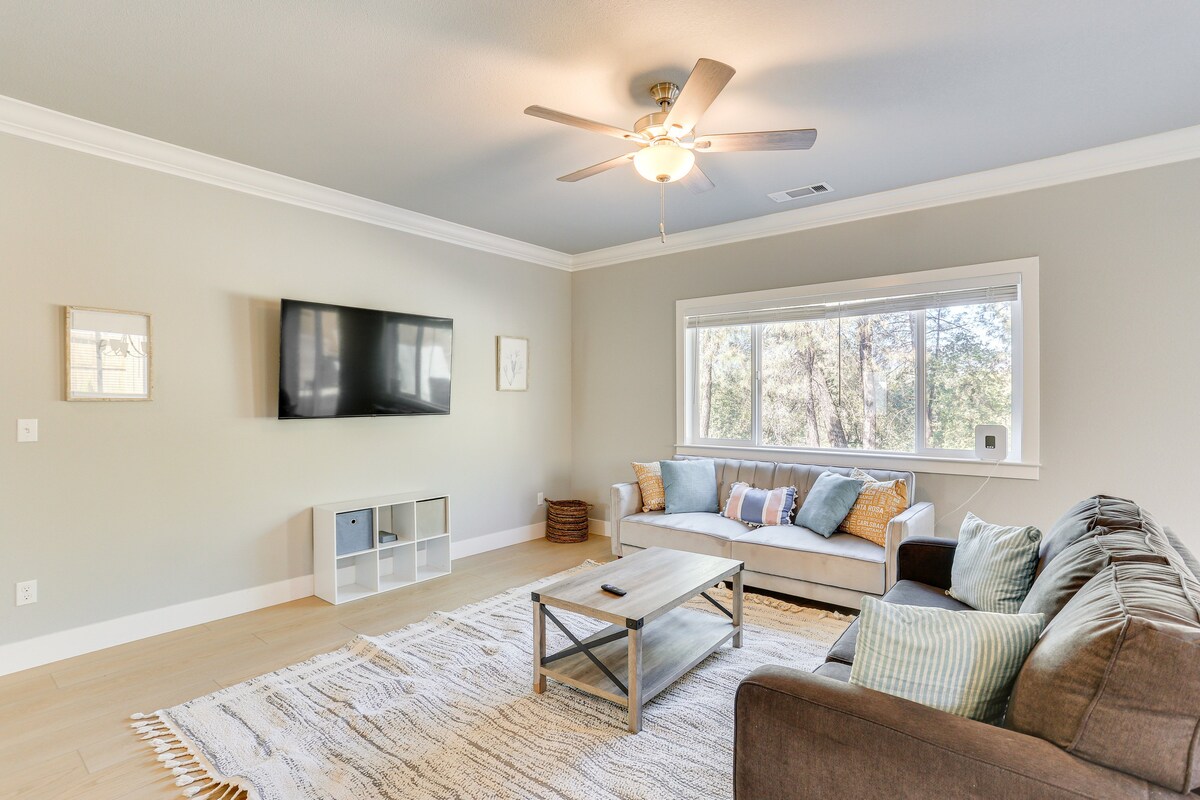
Close to I5: Newer Pet-friendly Home Near Bethel
House · 3 bd · 2 ba · sleeps 7 · 1.0 mi
Revenue $20,287ADR $142Occ ≈ 39%3.7★ (3)
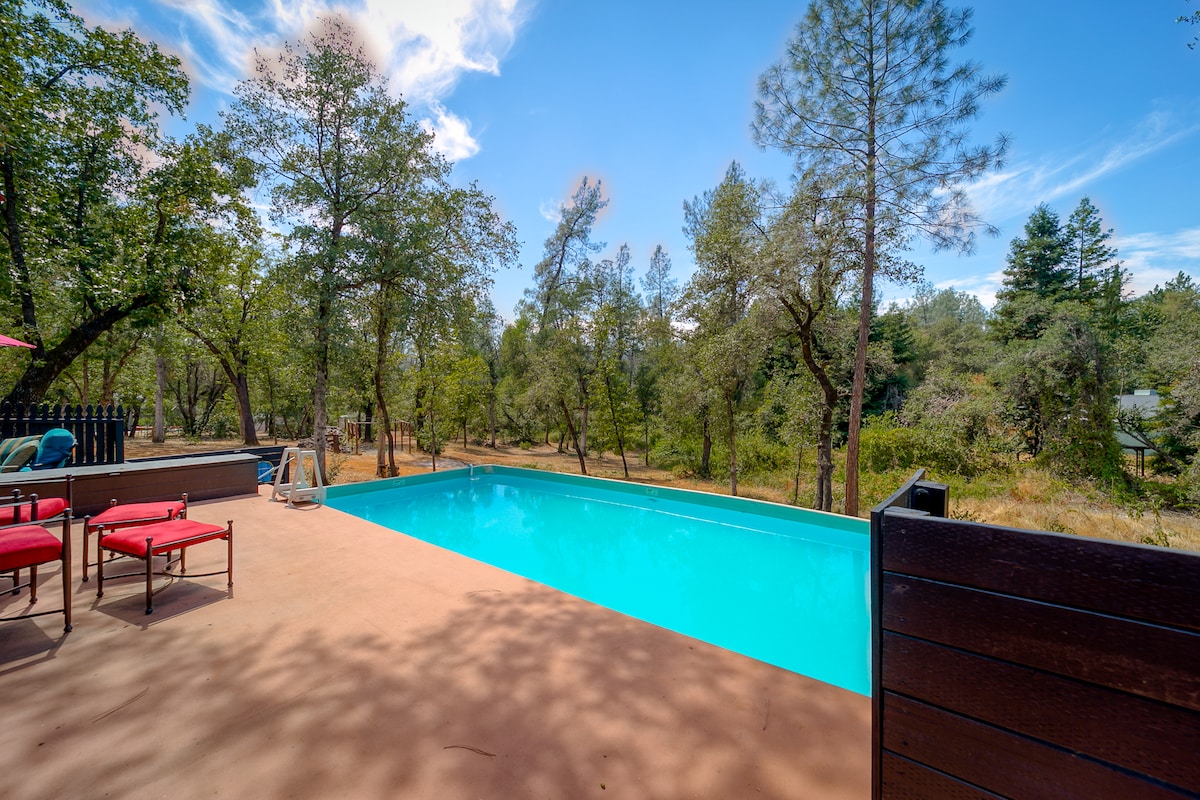
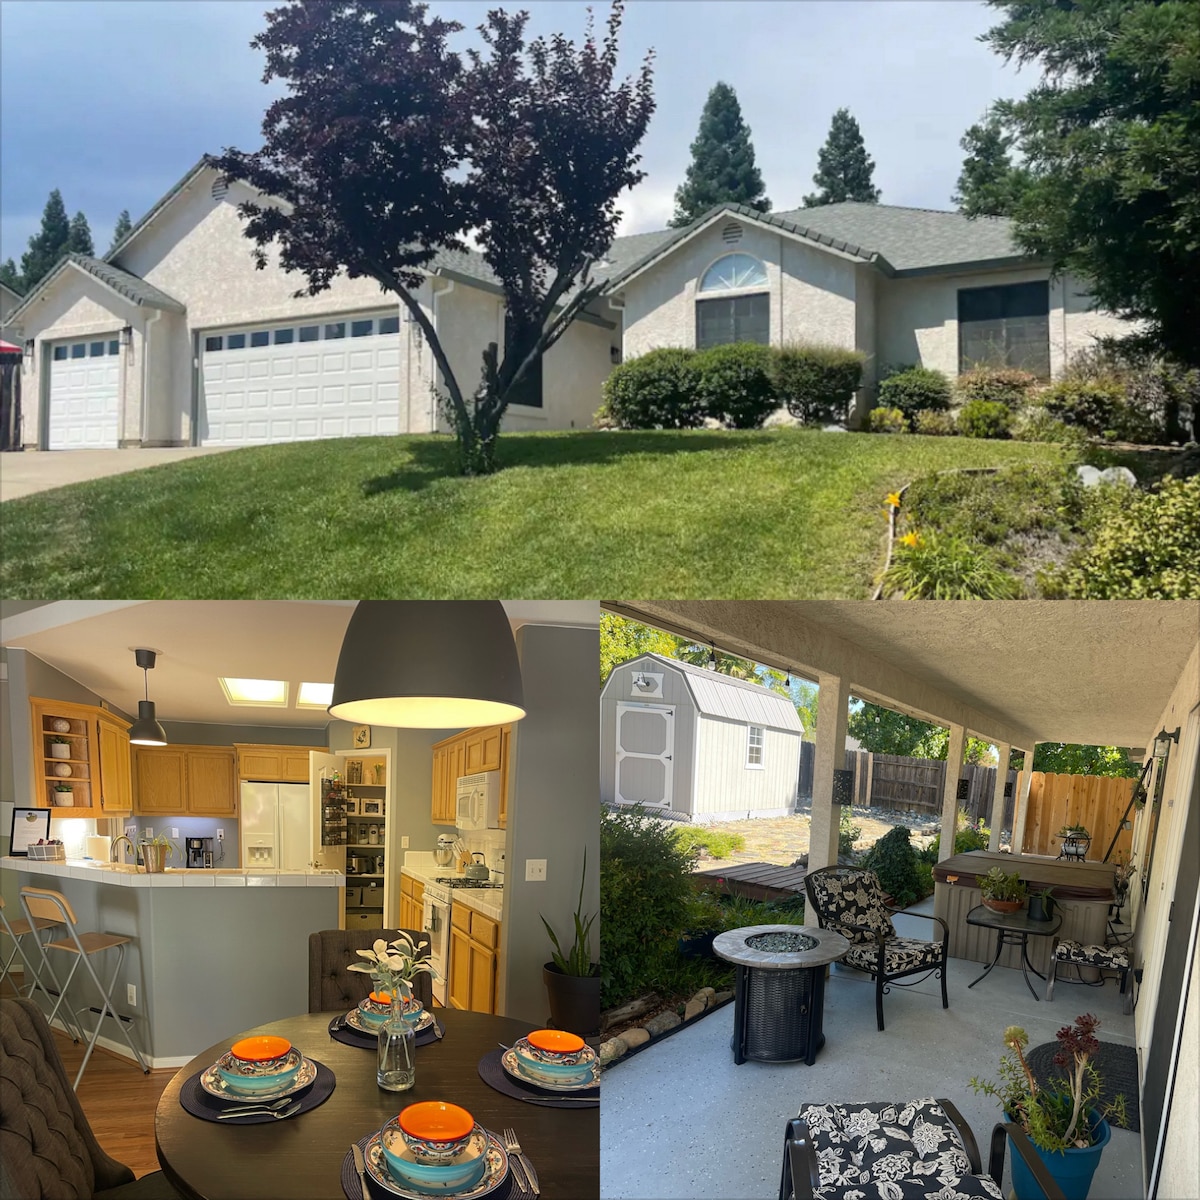
Shasta House
House · 3 bd · 2 ba · sleeps 6 · 1.8 mi
- Hot tub
- A/C
- Free parking
- Pets OK
- +4
Revenue $45,728ADR $190Occ ≈ 66%5★ (88)
| Listing | Size | Revenue (12 mo) | ADR | Occ ≈ | Rating | Distance | Links |
|---|---|---|---|---|---|---|---|
Home in Shasta Lake Near Redding: Early Check-In! House
| 3 bd · 2 ba · sleeps 8 | $39,899 | $232 | 47% | 5★ (79) | 0.7 mi | AirbnbVrboBooking |
White retreat-close to I5- Petfriendly near Bethel House
| 3 bd · 2 ba · sleeps 8 | $52,619 | $174 | 83% | 4.8★ (82) | 0.9 mi | AirbnbVrboBooking |
Close to I5: Newer Pet-friendly Home Near Bethel House | 3 bd · 2 ba · sleeps 7 | $20,287 | $142 | 39% | 3.7★ (3) | 1.0 mi | Airbnb |
*Family friendly *Hot Tub *2200 sq ft *2 acres House
| 3 bd · 2 ba · sleeps 9 | $55,919 | $259 | 59% | 4.7★ (129) | 1.1 mi | AirbnbVrbo |
Shasta House House
| 3 bd · 2 ba · sleeps 6 | $45,728 | $190 | 66% | 5★ (88) | 1.8 mi | Airbnb |
Revenue and nightly rate (ADR) are trailing-12-month figures per listing. Occupancy is estimated as revenue ÷ ADR ÷ 365 and can read high when revenue includes cleaning fees.
Cash flow calculator
Est. revenue
$42,798
NOI
$21,308
Cash flow /mo
$1,776
Cash needed
$346,996
Cash-on-cash (all cash)
6.1%
ROE (yr 1)
8.9%
Cap rate
6.8%
DSCR
—
Year-1 write-off
$103,326
Year-1 tax shield @ 32%
$33,064
Year-1 return on equity
- Cash flow (annual)$21,308
- Principal paydown (n/a, cash)$0
- Appreciation at%$9,447
Tax savings aren't counted. Turn on “Count tax savings in returns” above if you can use the losses.
Opex, cash-needed & tax-savings breakdown
Annual operating expenses
- Management (20% of revenue)$8,560
- Platform fees (3% of revenue)$1,284
- Maintenance / capex (5% of revenue)$2,140
- Utilities & supplies$4,200
- HOA$0
- Property tax$3,936
- Insurance (STR-rated)$1,842
Cash needed to close
- Purchase price (all cash)$314,900
- Closing costs (4.0%)$12,596
- Furnishing (bought new)$19,500
Tax savings if the STR loophole applies
- Tax shield @ 32%$33,064
Property tax, insurance rate and the land/building split come from this listing's county tax record; other assumptions match the daily feed (see tasks/plan.md).
The write-off comes from the cost segregation estimate below. Not tax advice.
Cost segregation estimate
An estimate from the listing: every part of the home is priced from national construction costs, less wear for age, and the price (less land) is spread over the parts in proportion. The headline is what a typical cost seg study would claim for this property. The answers below are optional refinements.
Depreciable basis
$271,000
Short-life (5/15-yr)
$84,000 · 31%
Year-1 deduction
$103,000
Year-1 tax shield @ 32%
$33,000
Land 14% (county tax record, assessed value split) · building $187,000 over 39 years · new furniture $20,000
Based on: 1,156 sq ft, built 1981, 3 bd / 2 ba, unfurnished, listing features (pool, fireplace, flooring types).
Try the cost segregation calculator on any property →
IRS-guide safe-harbor floor: $81,000 in year 1 (22% short-life, $26,000 tax shield), the conservative amount following the IRS audit guide's residential classification table.
- $9,400
Kitchen cabinetsdefault
$8,300 new × 40% good × 2.83 allocation
- $7,700
Kitchen countertopsdefault
$6,800 new × 40% good × 2.83 allocation
- $2,300
Decorative trimdefault
$2,000 new × 40% good × 2.83 allocation
- $300
Mirrorsdefault
$300 new × 40% good × 2.83 allocation
- $1,400
Shelvingdefault
$1,200 new × 40% good × 2.83 allocation
- $3,400
Window coverings (12)default
$3,000 new × 40% good × 2.83 allocation
- $8,400
Carpet, vinyl & laminate (100% of floors)listing
$7,400 new × 40% good × 2.83 allocation
- $7,400
Kitchen & laundry equipment plumbingdefault
$6,500 new × 40% good × 2.83 allocation
- $4,400
Kitchen, laundry & data equipment electricaldefault
$3,900 new × 40% good × 2.83 allocation
- $9,200
Appliances (range, microwave, dishwasher, disposal, refrigerator, washer, dryer)default
$8,100 new × 40% good × 2.83 allocation
- $19,500
Furniture bought newlisting
$19,500 new × 100% good · bought separately
- $10,000
Paving: driveway & walks (paved)default
$7,000 new × 50% good × 2.83 allocation
- $9,600
Landscaping (typical)default
$6,800 new × 50% good × 2.83 allocation
- $1,600
Patiosdefault
$1,100 new × 50% good × 2.83 allocation
- $1,600
Decks & porches (attached)default
$1,100 new × 50% good × 2.83 allocation
- $6,800
Pool (above-ground)listing
$6,000 new × 40% good × 2.83 allocation
- $141,500
Structure: foundation, framing, walls, windows, doors, roof, interior finishesdefault
$124,800 new × 40% good × 2.83 allocation
- $14,700
Building plumbing & fixturesdefault
$13,000 new × 40% good × 2.83 allocation
- $13,500
Building electrical & lightingdefault
$11,900 new × 40% good × 2.83 allocation
- $14,800
HVACdefault
$13,000 new × 40% good × 2.83 allocation
- $3,000
Fireplacelisting
$2,600 new × 40% good × 2.83 allocation
About the property
Depreciation schedule: typical cost seg study
| Year | 5-yr | 15-yr | Building | Total |
|---|---|---|---|---|
| 1 | $73,500 | $29,600 | $200 | $103,300 |
| 2 | $0 | $0 | $4,800 | $4,800 |
| 3 | $0 | $0 | $4,800 | $4,800 |
| 4 | $0 | $0 | $4,800 | $4,800 |
| 5 | $0 | $0 | $4,800 | $4,800 |
| 6+ | $0 | $0 | $168,000 | $168,000 |
| Total | $73,500 | $29,600 | $187,500 | $290,600 |
Model-based estimate, not an engineered cost segregation study. The IRS doesn’t approve studies; get a professional study before filing. Using these losses against W-2 income needs the short-term rental exception (average stay ≤7 days + material participation). The 39-year building life applies because stays average under 30 days, a separate test (27.5 years for a long-term rental). Federal only: California, Georgia and Wisconsin disallow bonus depreciation, Ohio adds back 5/6 of it, and Tennessee has no personal income tax. Not tax advice.
Market note
Rules differ by jurisdiction. City of Redding caps whole-home vacation rentals at 400 with a 600 ft spacing rule (300 ft with a physical buffer), and its permit is NOT transferable to a new owner. Shasta Lake city and unincorporated Shasta County allow permitted rentals with no cap found, but permits also do not transfer on sale. Lodging tax ~10% plus a 2% tourism assessment in Redding. Verify parcel eligibility with the city or county before you buy.