
1725 Mississippi St Unit 1727
La Crosse, WI 54601
$294,900
6 bd · 2 ba · 2,586 sqft · Listed today
View on Realtor.com →Year built
1897
Sqft
2,586
Lot sqft
8,276
HOA / mo
None
Furnished
No
List date
2026-10-21T02:06:16.000000Z
Revenue
Annual revenue
$79,902
ADR
$350
Occupancy
63%
Cleaning fees (12 mo)
$11,740
Confidence
High (72.86), 5 comps
Comp revenue range (p25 / median / p75)
Few similar-size comps were found, so all comps are shown.
Median revenue of shown comps: $69,254
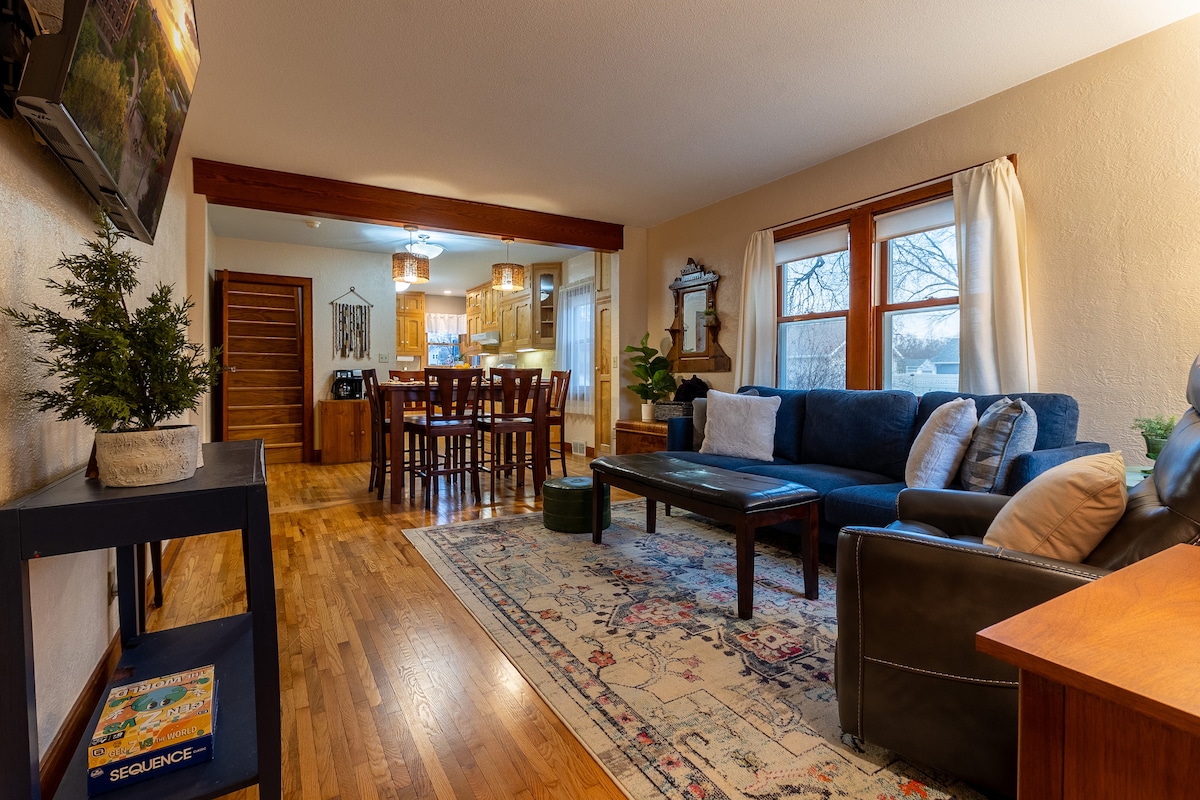
La Crosse's Bluffside Retreat
House · 5 bd · 2 ba · sleeps 8 · 0.5 mi
Revenue $60,324ADR $766Occ ≈ 22%4.8★ (22)
Delisted

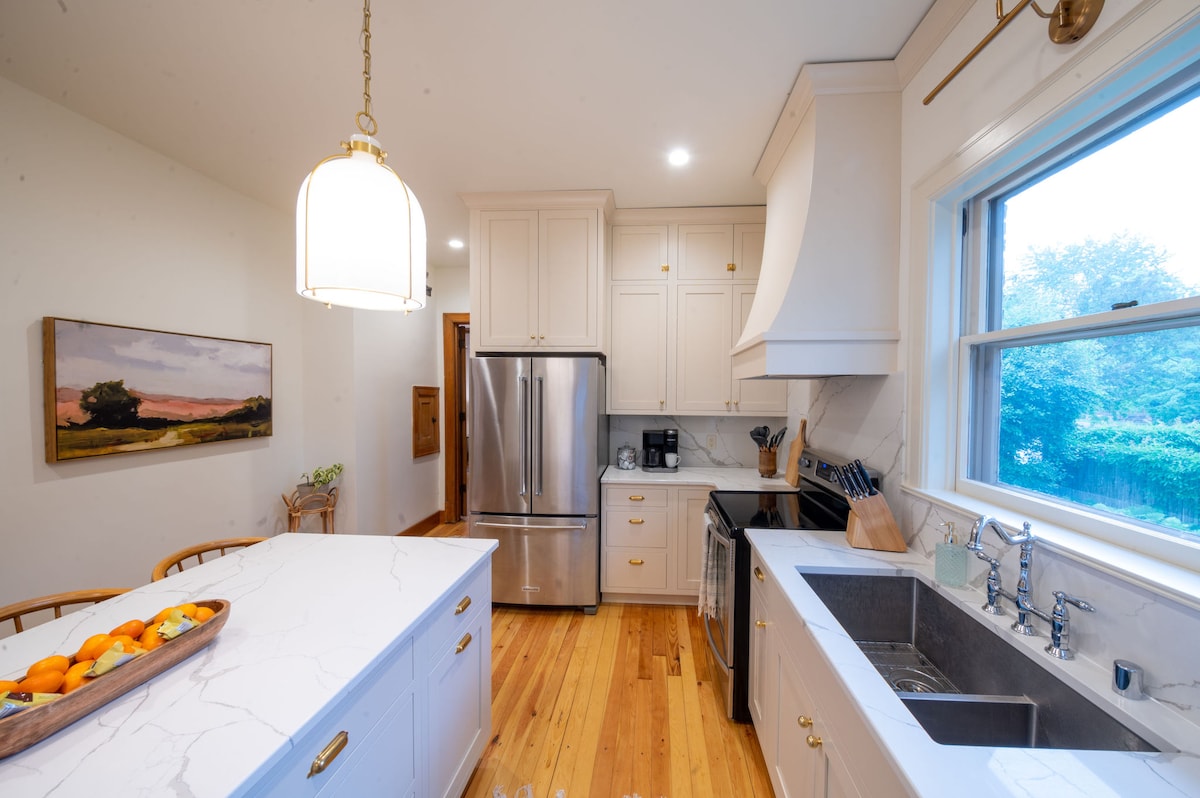
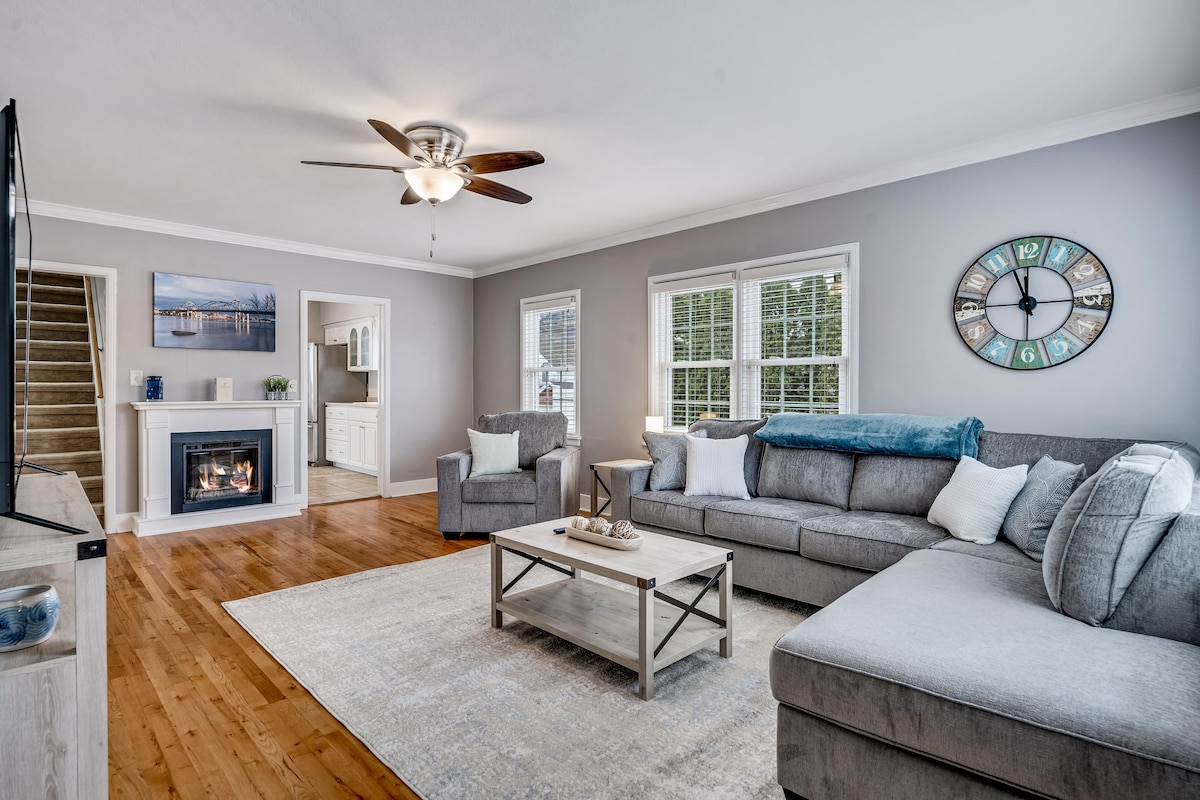
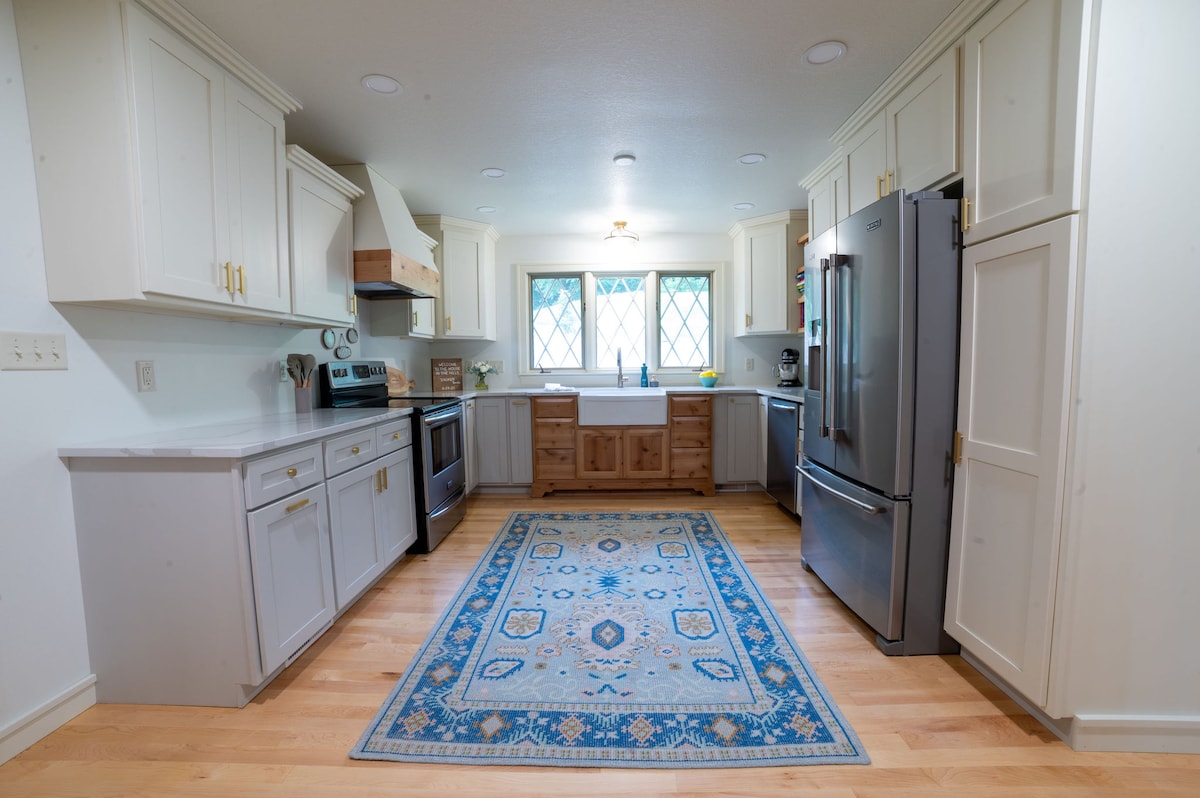
| Listing | Size | Revenue (12 mo) | ADR | Occ ≈ | Rating | Distance | Links |
|---|---|---|---|---|---|---|---|
La Crosse's Bluffside Retreat House | 5 bd · 2 ba · sleeps 8 | $60,324 | $766 | 22% | 4.8★ (22) | 0.5 mi | Delisted |
Cozy 5BR Duplex by Mayo, 50-ft Parking House
| 5 bd · 2 ba · sleeps 10 | $100,488 | $307 | 90% | 5★ (19) | 0.5 mi | AirbnbVrbo |
Mod Manor on Main- Celebrations, Reunions, Events House
| 6 bd · 2.5 ba · sleeps 15 | $69,254 | $573 | 33% | 4.9★ (127) | 0.7 mi | AirbnbVrbo |
King Beds | Fenced Yard | Near Downtown House
| 5 bd · 2 ba · sleeps 10 | $100,097 | $441 | 62% | 5★ (188) | 1.3 mi | AirbnbVrbo |
House in the Hills! Charming luxury right in town House
| 5 bd · 3 ba · sleeps 10 | $58,149 | $432 | 37% | 5★ (201) | 1.8 mi | AirbnbVrbo |
Revenue and nightly rate (ADR) are trailing-12-month figures per listing. Occupancy is estimated as revenue ÷ ADR ÷ 365 and can read high when revenue includes cleaning fees.
Cash flow calculator
Rate 8.15% = 7.40% Freddie Mac 30-yr avg (Oct 15) + 0.75% investor premium
Est. revenue
$79,902
NOI
$46,735
Cash flow /mo
$2,248
Cash needed
$115,521
Cash-on-cash
23.4%
ROE (yr 1)
32.6%
Cap rate
15.8%
DSCR
2.37
Year-1 write-off
$78,518
Year-1 tax shield @ 32%
$25,126
Year-1 return on equity
- Cash flow (annual)$26,982
- Principal paydown$1,793
- Appreciation at%$8,847
Tax savings aren't counted. Turn on “Count tax savings in returns” above if you can use the losses.
Opex, cash-needed & tax-savings breakdown
Annual operating expenses
- Management (20% of revenue)$15,980
- Platform fees (3% of revenue)$2,397
- Maintenance / capex (5% of revenue)$3,995
- Utilities & supplies$4,200
- HOA$0
- Property tax$5,135
- Insurance (STR-rated)$1,460
Cash needed to close
- Down payment (25%)$73,725
- Closing costs (4.0%)$11,796
- Furnishing (bought new)$30,000
Tax savings if the STR loophole applies
- Tax shield @ 32%$25,126
No county tax record split for property tax, insurance rate and the land/building split, so those use market defaults — edit the price above; other assumptions match the daily feed (see tasks/plan.md).
The write-off comes from the cost segregation estimate below. Not tax advice.
Cost segregation estimate
An estimate from the listing: every part of the home is priced from national construction costs, less wear for age, and the price (less land) is spread over the parts in proportion. The headline is what a typical cost seg study would claim for this property. The answers below are optional refinements.
Depreciable basis
$242,000
Short-life (5/15-yr)
$48,000 · 20%
Year-1 deduction
$79,000
Year-1 tax shield @ 32%
$25,000
Land 18% (market default, no usable tax-record split) · building $194,000 over 39 years · new furniture $30,000
Based on: 2,586 sq ft, built 1897, 6 bd / 2 ba, unfurnished, listing features (appliance list).
Try the cost segregation calculator on any property →
IRS-guide safe-harbor floor: $63,000 in year 1 (13% short-life, $20,000 tax shield), the conservative amount following the IRS audit guide's residential classification table.
- $5,900
Kitchen cabinetsdefault
$11,500 new × 40% good × 1.28 allocation
- $4,800
Kitchen countertopsdefault
$9,400 new × 40% good × 1.28 allocation
- $2,300
Decorative trimdefault
$4,500 new × 40% good × 1.28 allocation
- $200
Mirrorsdefault
$300 new × 40% good × 1.28 allocation
- $1,100
Shelvingdefault
$2,100 new × 40% good × 1.28 allocation
- $3,300
Window coverings (26)default
$6,500 new × 40% good × 1.28 allocation
- $3,400
Carpet, vinyl & laminate (40% of floors)default
$6,700 new × 40% good × 1.28 allocation
- $4,600
Kitchen & laundry equipment plumbingdefault
$8,900 new × 40% good × 1.28 allocation
- $2,800
Kitchen, laundry & data equipment electricaldefault
$5,400 new × 40% good × 1.28 allocation
- $3,600
Appliances (range, dishwasher, refrigerator, washer, dryer)listing
$7,000 new × 40% good × 1.28 allocation
- $30,000
Furniture bought newlisting
$30,000 new × 100% good · bought separately
- $6,700
Paving: driveway & walks (paved)default
$10,500 new × 50% good × 1.28 allocation
- $6,500
Landscaping (typical)default
$10,100 new × 50% good × 1.28 allocation
- $1,600
Patiosdefault
$2,600 new × 50% good × 1.28 allocation
- $1,600
Decks & porches (attached)default
$2,600 new × 50% good × 1.28 allocation
- $143,200
Structure: foundation, framing, walls, windows, doors, roof, interior finishesdefault
$280,200 new × 40% good × 1.28 allocation
- $14,900
Building plumbing & fixturesdefault
$29,100 new × 40% good × 1.28 allocation
- $15,400
Building electrical & lightingdefault
$30,100 new × 40% good × 1.28 allocation
- $14,900
HVACdefault
$29,100 new × 40% good × 1.28 allocation
- $5,100
Hardwood & tile floorsdefault
$10,000 new × 40% good × 1.28 allocation
About the property
Depreciation schedule: typical cost seg study
| Year | 5-yr | 15-yr | Building | Total |
|---|---|---|---|---|
| 1 | $61,800 | $16,500 | $200 | $78,500 |
| 2 | $0 | $0 | $5,000 | $5,000 |
| 3 | $0 | $0 | $5,000 | $5,000 |
| 4 | $0 | $0 | $5,000 | $5,000 |
| 5 | $0 | $0 | $5,000 | $5,000 |
| 6+ | $0 | $0 | $173,500 | $173,500 |
| Total | $61,800 | $16,500 | $193,500 | $271,800 |
Model-based estimate, not an engineered cost segregation study. The IRS doesn’t approve studies; get a professional study before filing. Using these losses against W-2 income needs the short-term rental exception (average stay ≤7 days + material participation). The 39-year building life applies because stays average under 30 days, a separate test (27.5 years for a long-term rental). Federal only: California, Georgia and Wisconsin disallow bonus depreciation, Ohio adds back 5/6 of it, and Tennessee has no personal income tax. Not tax advice.
Market note
Rules differ by jurisdiction. The City of La Crosse requires a short-term rental license ($100 a year) once you rent more than 10 nights a year, plus a Wisconsin tourist rooming house license and inspection from the La Crosse County Health Department. We found no owner-occupancy rule or night cap in the city, but the license does NOT transfer to a new owner. Onalaska allows rentals with a city permit in some zoning districts, and unincorporated towns follow La Crosse County zoning, which has its own permit and day limits. Wisconsin law lets local governments restrict stays under 7 nights. Verify parcel eligibility with the city or county before you buy.