
920 Zeisler St
La Crosse, WI 54601
$259,900
2 bd · 2 ba · 1,600 sqft · Listed 1d ago
View on Realtor.com →Year built
1958
Sqft
1,600
Lot sqft
4,356
HOA / mo
None
Furnished
No
List date
2026-10-04T21:48:41.000000Z
Revenue
Annual revenue
$36,454
ADR
$184
Occupancy
54%
Cleaning fees (12 mo)
$9,780
Confidence
High (75.82), 6 comps
Comp revenue range (p25 / median / p75)
Median revenue of shown comps: $36,134
| Listing | Size | Revenue (12 mo) | ADR | Occ ≈ | Rating | Distance | Links |
|---|---|---|---|---|---|---|---|
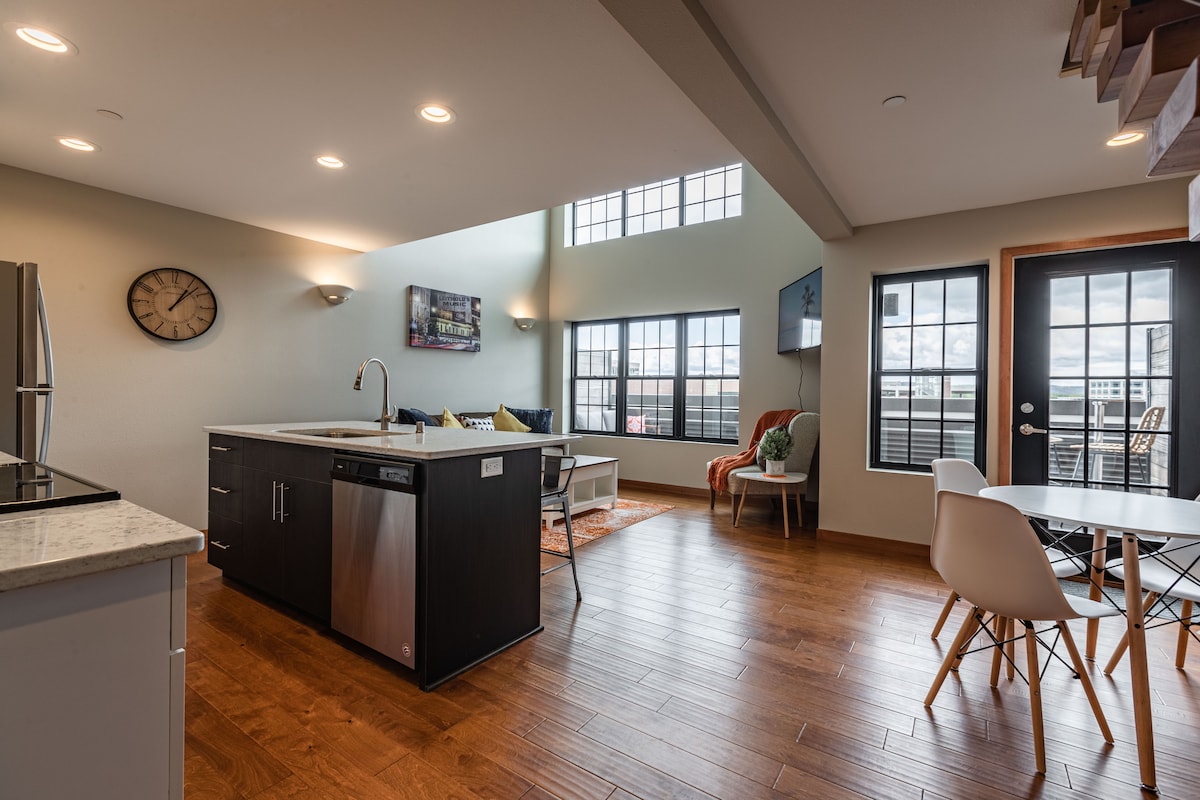 Lovely, modern condo close to dining and shopping! Loft | 2 bd · 1.5 ba · sleeps 6 | $40,855 | $198 | 57% | 4.9★ (233) | 0.3 mi | AirbnbVrbo |
 River City Apartment with Office/Flex space Apartment | 2 bd · 1 ba · sleeps 5 | $32,333 | $149 | 59% | 4.8★ (32) | 0.6 mi | AirbnbVrboBooking |
 River City Apartment: Downtown 2BR with Parking Apartment | 2 bd · 1 ba · sleeps 5 | $34,246 | $163 | 58% | 4.8★ (37) | 0.6 mi | AirbnbVrboBooking |
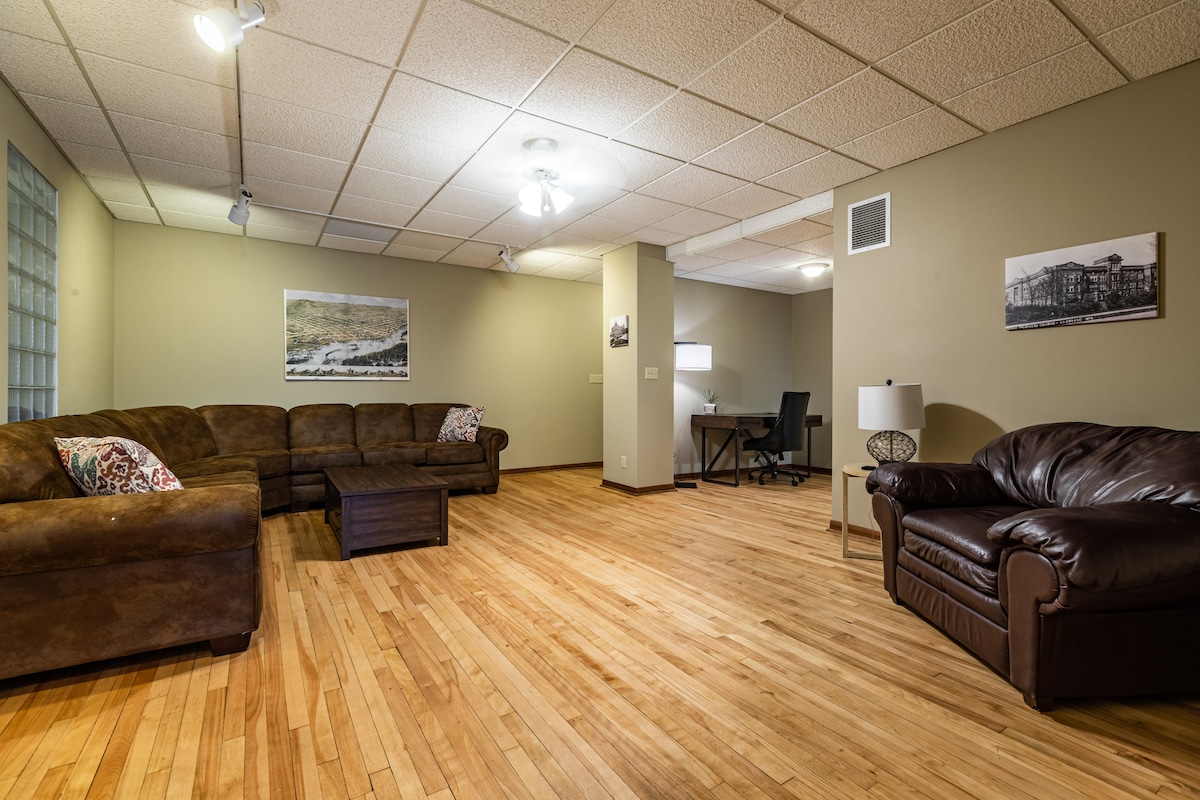 Historic Downtown Top Floor 2BR Apartment Apartment | 2 bd · 1 ba · sleeps 8 | $22,551 | $178 | 35% | 4.8★ (108) | 0.6 mi | AirbnbVrbo |
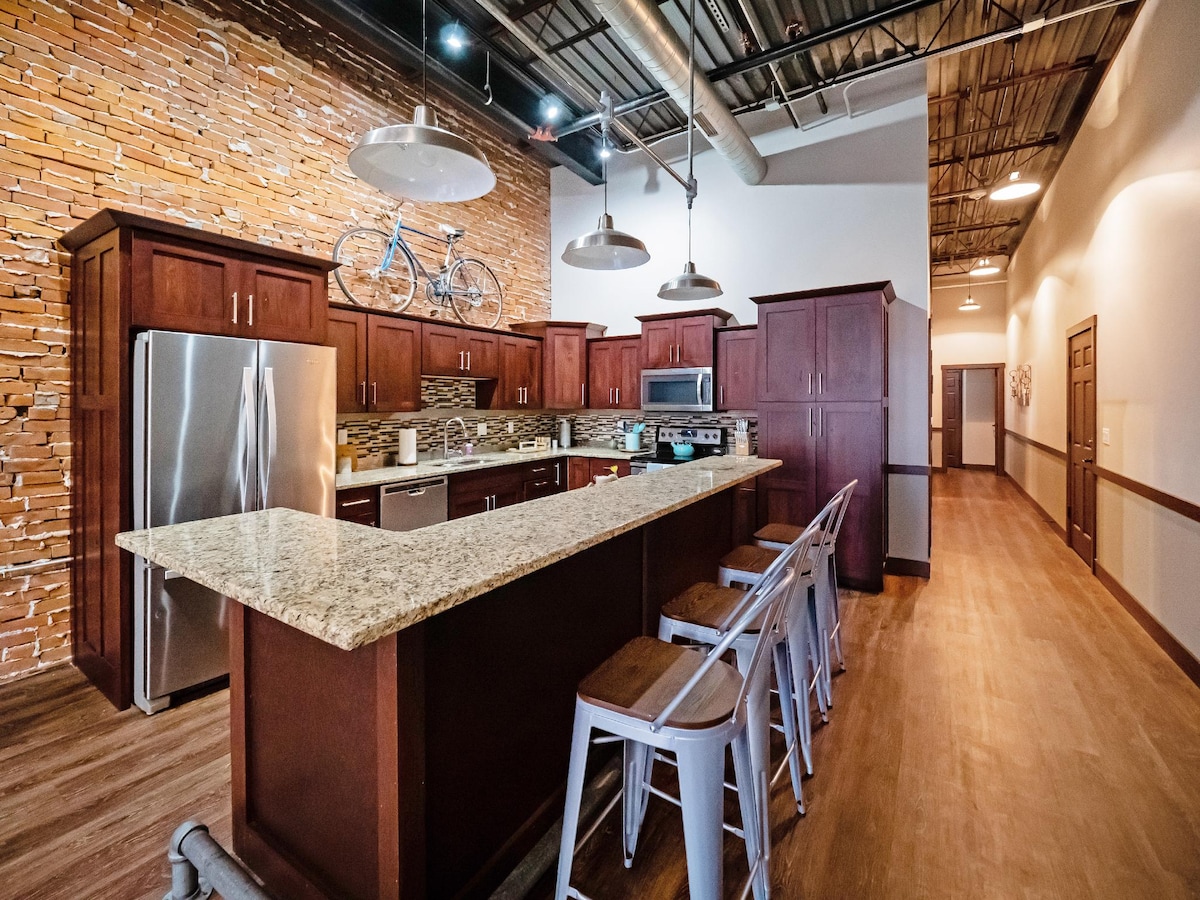 Modern Downtown La Crosse Apartment Apartment | 2 bd · 2 ba · sleeps 4 | $38,021 | $184 | 57% | 4.8★ (200) | 0.7 mi | AirbnbVrboBooking |
 Modern Flat in Downtown La Crosse Apartment | 2 bd · 2 ba · sleeps 4 | $48,474 | $197 | 67% | 4.8★ (261) | 0.7 mi | AirbnbVrboBooking |
Revenue and nightly rate (ADR) are trailing-12-month figures per listing. Occupancy is estimated as revenue ÷ ADR ÷ 365 and can read high when revenue includes cleaning fees.
Cash flow calculator
Rate 8.03% = 7.28% Freddie Mac 30-yr avg (Oct 1) + 0.75% investor premium
Est. revenue
$36,454
NOI
$17,038
Cash flow /mo
-$15
Cash needed
$91,371
Cash-on-cash
-0.2%
ROE (yr 1)
10.1%
Cap rate
6.6%
DSCR
0.99
Year-1 write-off
$64,847
Year-1 tax shield @ 32%
$20,751
Year-1 return on equity
- Cash flow (annual)-$174
- Principal paydown$1,619
- Appreciation at%$7,797
Tax savings aren't counted. Turn on “Count tax savings in returns” above if you can use the losses.
Opex, cash-needed & tax-savings breakdown
Annual operating expenses
- Management (20% of revenue)$7,291
- Platform fees (3% of revenue)$1,094
- Maintenance / capex (5% of revenue)$1,823
- Utilities & supplies$4,200
- HOA$0
- Property tax$3,722
- Insurance (STR-rated)$1,287
Cash needed to close
- Down payment (25%)$64,975
- Closing costs (4.0%)$10,396
- Furnishing (bought new)$16,000
Tax savings if the STR loophole applies
- Tax shield @ 32%$20,751
Property tax, insurance rate and the land/building split come from this listing's county tax record; other assumptions match the daily feed (see tasks/plan.md).
The write-off comes from the cost segregation estimate below. Not tax advice.
Cost segregation estimate
An estimate from the listing: every part of the home is priced from national construction costs, less wear for age, and the price (less land) is spread over the parts in proportion. The headline is what a typical cost seg study would claim for this property. The answers below are optional refinements.
Depreciable basis
$213,000
Short-life (5/15-yr)
$49,000 · 23%
Year-1 deduction
$65,000
Year-1 tax shield @ 32%
$21,000
Land 18% (county tax record, assessed value split) · building $165,000 over 39 years · new furniture $16,000
Based on: 1,600 sq ft, built 1958, 2 bd / 2 ba, unfurnished, listing features (appliance list).
Try the cost segregation calculator on any property →
IRS-guide safe-harbor floor: $49,000 in year 1 (15% short-life, $16,000 tax shield), the conservative amount following the IRS audit guide's residential classification table.
- $6,600
Kitchen cabinetsdefault
$9,300 new × 40% good × 1.76 allocation
- $5,400
Kitchen countertopsdefault
$7,600 new × 40% good × 1.76 allocation
- $2,000
Decorative trimdefault
$2,800 new × 40% good × 1.76 allocation
- $200
Mirrorsdefault
$300 new × 40% good × 1.76 allocation
- $600
Shelvingdefault
$900 new × 40% good × 1.76 allocation
- $2,800
Window coverings (16)default
$4,000 new × 40% good × 1.76 allocation
- $2,900
Carpet, vinyl & laminate (40% of floors)default
$4,100 new × 40% good × 1.76 allocation
- $5,100
Kitchen & laundry equipment plumbingdefault
$7,200 new × 40% good × 1.76 allocation
- $3,100
Kitchen, laundry & data equipment electricaldefault
$4,400 new × 40% good × 1.76 allocation
- $2,800
Appliances (range, refrigerator)listing
$4,000 new × 40% good × 1.76 allocation
- $16,000
Furniture bought newlisting
$16,000 new × 100% good · bought separately
- $7,300
Paving: driveway & walks (paved)listing
$8,300 new × 50% good × 1.76 allocation
- $7,000
Landscaping (typical)default
$8,000 new × 50% good × 1.76 allocation
- $1,400
Patiosdefault
$1,600 new × 50% good × 1.76 allocation
- $1,400
Decks & porches (attached)default
$1,600 new × 50% good × 1.76 allocation
- $122,600
Structure: foundation, framing, walls, windows, doors, roof, interior finishesdefault
$173,600 new × 40% good × 1.76 allocation
- $12,700
Building plumbing & fixturesdefault
$18,000 new × 40% good × 1.76 allocation
- $12,400
Building electrical & lightingdefault
$17,600 new × 40% good × 1.76 allocation
- $12,700
HVACdefault
$18,000 new × 40% good × 1.76 allocation
- $4,400
Hardwood & tile floorsdefault
$6,200 new × 40% good × 1.76 allocation
About the property
Depreciation schedule: typical cost seg study
| Year | 5-yr | 15-yr | Building | Total |
|---|---|---|---|---|
| 1 | $47,500 | $17,100 | $200 | $64,800 |
| 2 | $0 | $0 | $4,200 | $4,200 |
| 3 | $0 | $0 | $4,200 | $4,200 |
| 4 | $0 | $0 | $4,200 | $4,200 |
| 5 | $0 | $0 | $4,200 | $4,200 |
| 6+ | $0 | $0 | $147,700 | $147,700 |
| Total | $47,500 | $17,100 | $164,700 | $229,400 |
Model-based estimate, not an engineered cost segregation study. The IRS doesn’t approve studies; get a professional study before filing. Using these losses against W-2 income needs the short-term rental exception (average stay ≤7 days + material participation). The 39-year building life applies because stays average under 30 days, a separate test (27.5 years for a long-term rental). Federal only: California, Georgia and Wisconsin disallow bonus depreciation, Ohio adds back 5/6 of it, and Tennessee has no personal income tax. Not tax advice.
Market note
Rules differ by jurisdiction. The City of La Crosse requires a short-term rental license ($100 a year) once you rent more than 10 nights a year, plus a Wisconsin tourist rooming house license and inspection from the La Crosse County Health Department. We found no owner-occupancy rule or night cap in the city, but the license does NOT transfer to a new owner. Onalaska allows rentals with a city permit in some zoning districts, and unincorporated towns follow La Crosse County zoning, which has its own permit and day limits. Wisconsin law lets local governments restrict stays under 7 nights. Verify parcel eligibility with the city or county before you buy.